Source: Unite.AI
A company’s cash has two jobs: stay available for the next payment and earn something while it waits. Spiko is building the infrastructure to make those jobs work together, with software deciding when money should remain liquid and when it can be put to work.
The London- and Paris-based fintech has announced a $90 million Series B led by New Enterprise Associates (NEA), bringing its total funding to $120 million. Participants include Index Ventures, Speedinvest, White Star Capital, the founders of Qonto, and former Bundesbank president Axel Weber. Spiko says the capital will support new funds, expansion into new markets, and hiring.
The financing comes as the company reports more than $2.7 billion in assets under management, more than fivefold AUM growth over the past year, and over 10,000 business and individual customers across more than 25 jurisdictions. Its ambition reaches beyond providing another place to park cash: Spiko wants yield-bearing fund shares to become a programmable component of financial applications, treasury systems, and eventually AI-driven workflows.
From Idle Balances to an Automated Treasury
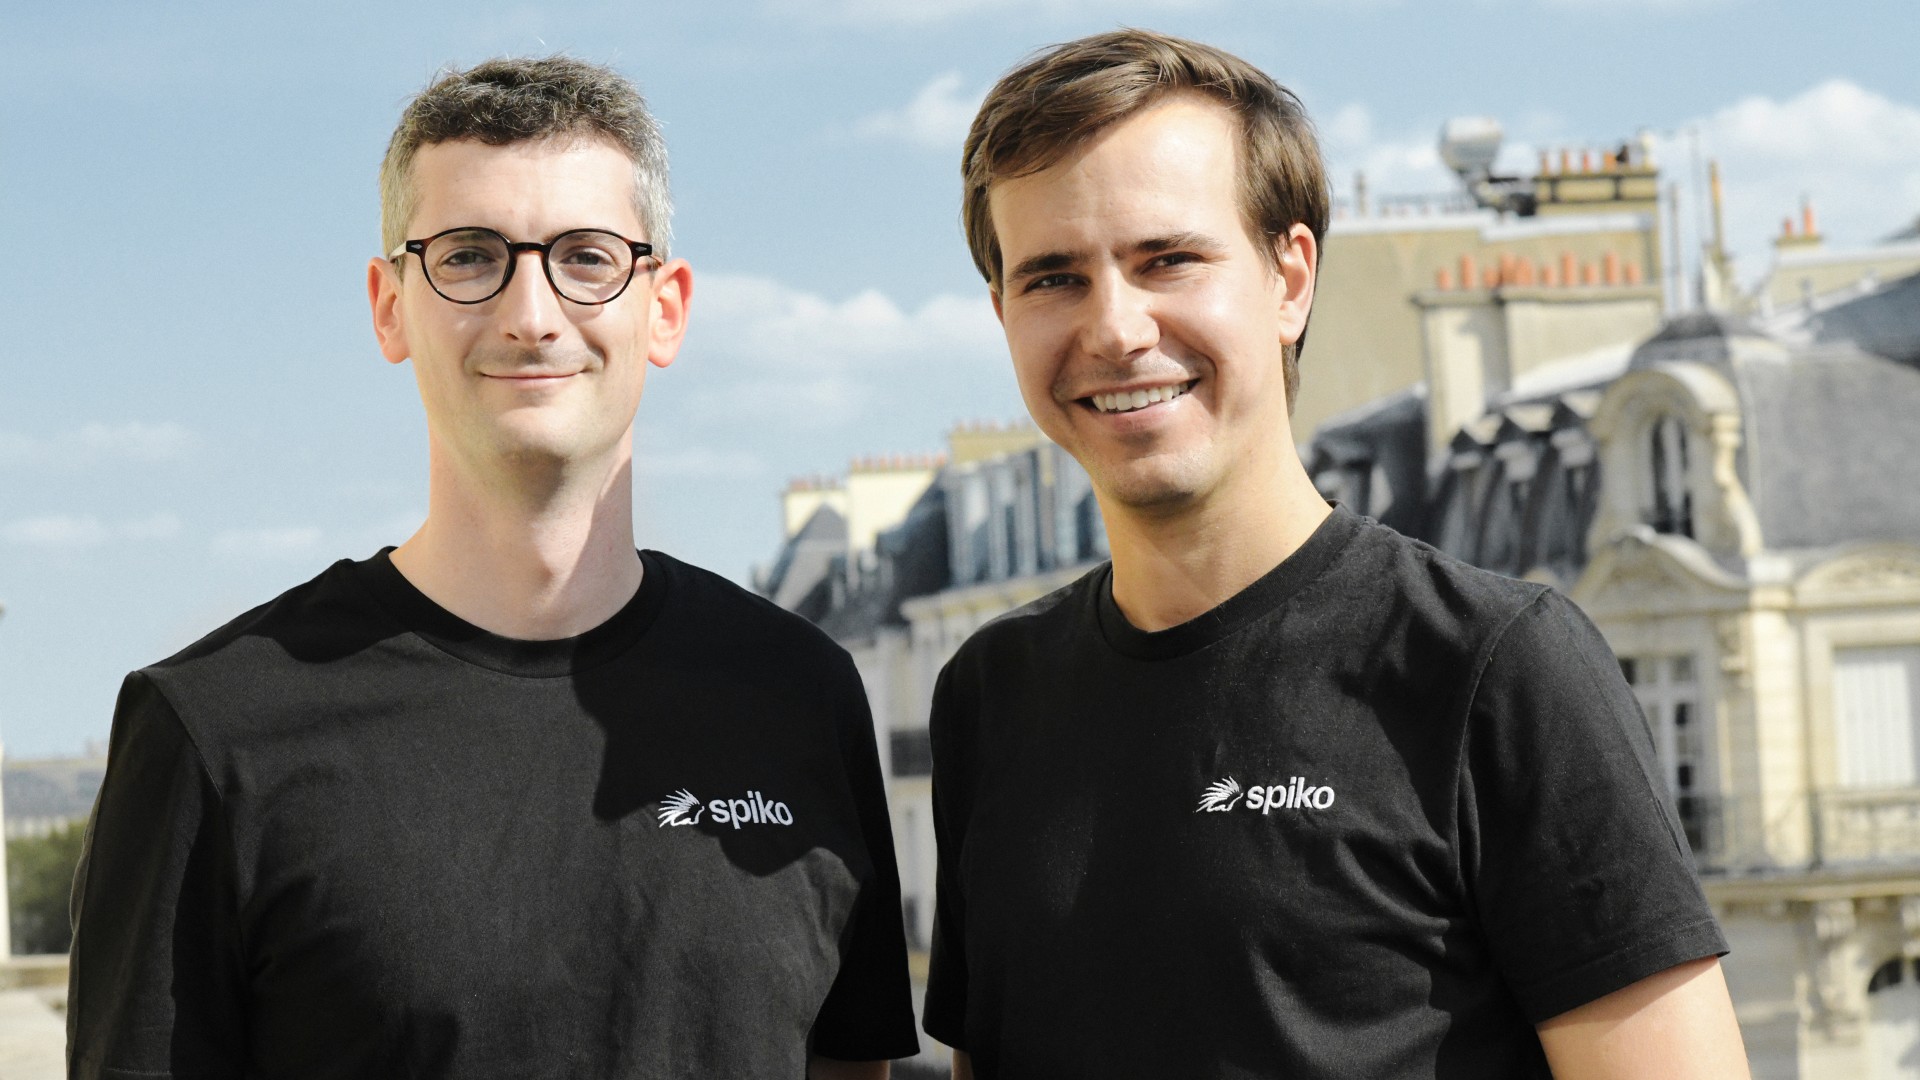
Founded in 2023 by Paul-Adrien Hyppolite and Antoine Michon, Spiko combines financial-market experience with a software infrastructure approach. Hyppolite previously served as Deputy Head of the Financial Markets division at the French Treasury. Michon was a technology adviser to the French government and previously led deployments at Palantir.
The founders are targeting a familiar mismatch. Businesses need working capital available for payroll, suppliers, and unexpected expenses, but keeping an unnecessarily large operating balance can mean giving up returns. Moving that surplus manually creates its own work: calculating what can be invested, placing orders, checking settlement, and getting money back before a bill is due.
“Every person and every organization holds cash, yet whether it earns anything still depends on who you are and how much you have,” Hyppolite said in the announcement. “Yield should be universal. Our ambition is to make all cash earn by default, around the clock.”
Spiko offers access through desktop and mobile applications, while financial platforms can embed its funds through APIs. The company’s announcement describes cash funds spanning euros, dollars, pounds sterling, and Swiss francs, serving customers ranging from startups and medical practices to research institutes, public institutions, and venture capital funds.
What Tokenization Actually Changes
The technology begins with how ownership is recorded. Spiko’s tokenization documentation explains that blockchain networks serve as the registry for fund shares. Investors hold an interest in a fund, represented digitally by a token; the blockchain supplies the infrastructure for recording and transferring that interest.
That separation matters. A tokenized Treasury-bill fund derives its investment exposure from the underlying securities. The token is the ownership representation, rather than a separate source of yield. Spiko says customers can opt to hold shares in their own wallets, while those using its managed interface do not need to interact directly with the blockchain.
According to its transfer documentation, shares can only be held by allowlisted wallet addresses and can move between those approved addresses. Supported networks include Ethereum, Polygon PoS, Arbitrum One, Etherlink, Base, Starknet, and Stellar. The documented token standards include ERC-20 and ERC-1363.
The result combines an open technical network with controlled access to a regulated financial product. It gives software a way to work with fund ownership while maintaining eligibility checks. Spiko describes share transfers as available around the clock, a useful foundation for applications whose activity continues after traditional market hours.
The API Layer Makes Cash Usable by Software
Tokenization is only one part of the system. Spiko’s developer documentation separates its interfaces into three functions: public financial data, management of an investor’s account, and distribution of funds through partner platforms.
The Public API exposes fund and portfolio information, yields, and share-class data. The Investor API lets authorized integrations read positions and submit or track deposit and withdrawal orders. The Distributor API supports investor management and order handling for platforms embedding Spiko’s products. This gives a fintech a route to offer fund access within its own experience and gives a finance team a route to connect treasury operations to existing software.
The Investor API supports API-key authentication for server-side integrations and OAuth 2.0 for applications acting with a user’s authorization. Its documented functions include transaction tracking and data exports for accounting and reconciliation. These less visible capabilities are essential to automation: a system must be able to establish what it holds, request a change, and record the outcome.
Where AI Agents Fit Into the Cash Workflow
Spiko’s announcement illustrates its treasury vision with rules a finance team could set once: keep enough money in the operating account for payroll and suppliers, sweep the excess into a liquid fund, and allocate cash that will not be needed for a quarter to a term product. A treasury management system, or an AI agent working on the company’s behalf, could adjust that program through the API.
The AI connection is therefore about execution infrastructure. An assistant can analyze a cash forecast, but acting on that analysis requires an authorized interface to positions and orders. Spiko provides that interface; the announcement does not describe a proprietary AI model making investment decisions.
For an agent-connected treasury system, the distinction between proposing a change and authorizing it would remain central. A forecast may indicate surplus cash, yet the operating buffer and permitted products still come from the business’s policy. The API supplies a path from those rules to an order, with the finance team retaining responsibility for the constraints.
Spiko’s access-management documentation supports different roles for viewing balances and initiating transactions. Its website also describes two-factor authentication for critical functions and an optional dual-approval mode for sensitive actions. Those controls provide useful context for its automation ambitions, without establishing that a fully autonomous AI treasury product has already been deployed.
Around-the-Clock Infrastructure Has Practical Limits
There are several different clocks in this system: blockchain transfers, withdrawal processing, fund valuation, and interest accrual. Making one continuous does not automatically make all of them continuous.
Spiko’s withdrawal documentation describes 24/7 instant euro withdrawals using SEPA Instant, with a limit of €500,000 per day. Standard withdrawals have settlement schedules and cutoff times that depend on the product and currency. Its valuation documentation says the official net asset value of its money market funds is calculated by the fund administrator on each business day.
The fundraising announcement also distinguishes instant withdrawals available today from continuously accruing yield that the company says is coming soon. The latter is part of the roadmap, rather than something readers should assume applies to every current fund.
The range of underlying products matters as well. Alongside Treasury-bill money market funds, Spiko documents Smart Cash, a UCITS fund that combines a securities portfolio with a total return swap. Under that arrangement, the fund exchanges the portfolio’s performance with a bank counterparty for an overnight-rate-based return plus a spread. That is a different structure from holding Treasury bills and introduces counterparty exposure. Tokenizing both products does not make their investment characteristics identical.
The Next Phase Is Distribution at Scale
Spiko says it is building local teams across Europe, including Germany, Italy, Spain, the Netherlands, and the Nordics. Its growth strategy combines a direct treasury product with distribution through other financial platforms, giving the company multiple routes to customers whose cash-management needs vary by currency, institution, and market.
The company describes itself as the world’s largest issuer of tokenized cash funds. That is its stated market position; its more concrete reported milestone is the $2.7 billion already entrusted to its funds. The new financing provides resources to extend that base through a broader product range and more local distribution.
Spiko’s pitch is compelling because it connects yield to the everyday movement of money. A fund that earns a return is useful; a fund that can be integrated into the systems deciding when cash is needed could become part of the business’s operating infrastructure. The $90 million round backs Spiko’s effort to make that connection routine, with APIs and tokenized ownership providing the technical foundation.